
Inflation and deflation are not the normal subjects for this blog. Those who follow my personal social media accounts realize I am not just a watch innovator but also an investor. Saying I am an investor is like saying you are a watch collector – it covers a multitude of sins.
When I tell someone I am an investor, each person will conjure up a different image for each person. Just as we looked into the difference between a watch collector and a collector of watches, there are differences in the investment community too. Some may call me a trader rather than an investor, to me that is semantics. I believe an investor is anyone who seeks to manage their money in any market actively. I consider The Watch Whisperer to be an investor – he just happens to invest in classic watches and cars.
What If The Unusual Is Correct?
The last 12 months have been a challenging time for all investors. There has been tremendous volatility. The financial markets of all kinds have been moving in unusual ways. Anyone short GameStop recently can attest to that. Or owners of a barrel of oil in April 2020. Some may say the markets are irrational – but what if they are rational? What if the markets are showing us the way?
 On 20 April 2020, You Were Paid To “Buy” a Barrel Of Oil
This question has been nagging me as I look at the investment landscape. Especially the $10…$14…$18 trillion of bonds around the world that trade with a negative interest rate. What does that imply for our future? Negative interest rates seem naturally wrong. The trouble is, what if they signal something we should all be taking notice of?
Asking The Painful Question
These nagging doubts were crystallized when a very talented group of money managers wrote the following.
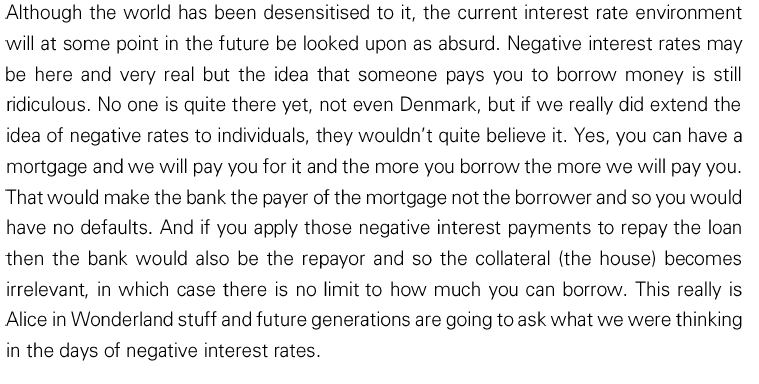 Read Once, This Appears Completely Rational. Only When Diving a Bit Deeper Do The Differences Between and Inflation and Deflation Investment Environment Become Evident.
There are several points made here, but the one that stuck with me was, “… the idea that someone pays you to borrow money is still ridiculous.” Is it? Before 20 April 2020, it was ridiculous to think you could be paid to buy a barrel of oil.
Ridiculous Has A Bad History
Nicolaus Copernicus was thought ridiculous (and perhaps worse) when he suggested that the earth orbited the sun rather than the other way around. The sweeping statement by this money manager compelled me to sit down and explore if I thought he was correct. In the process perhaps I could clarify my thinking and hopefully further my understanding.
It Is Also Personal – Deflation Up Close
I hope you will indulge me. The reason is I feel I have seen this before. While Daniel was a young man selling watches in the Middle East, I was a young man trading equity derivatives in Tokyo. The year was 1994 and deflation was the last thing I ever thought possible. It was a painful education I went through. Twenty-five years later, Japan has endured consistent deflation. This is regardless of the quantity of money the Japanese central bank prints or how many rounds of stimulus and emergency budgets have been enacted. Deflation is ingrained in Japan.
As we sit here today, four central banks worldwide are committed to printing money – the United States Federal Reserve, the European Central Bank, the Bank of Japan, and the Bank of England. Interest rates are at all-time lows in many parts of the world. If inflation were around the corner, why are material portions of the global bond market trading at negative yields?
The Bank Of Japan Is Very Talented At Creating Money. Alas, There Seems No Correlation With Inflation. source: tradingeconomics.com
Can We Learn From Japan?
Could it be that the Japan situation is going global? I can attest from living in Japan from 1994 to 2011 and still closely following their economic situation that deflation is a creeping and insidious force of nature. You can see from the chart above that it appears that no amount of money printing can defeat it. What creates the circumstances for deflation to take hold, and are we now looking at that scenario globally?
Who Is Asking?
This is a question that my friend Ken Shirley and I have discussed for over two years now. Ken also spent a considerable time living and working in Japan. He spent ten years as the analyst and one of the portfolio managers for Nippon Partners, a value investment fund created by Jim Grant of Grant’s Interest Rate Observer fame and referenced in the film, The Big Short.
During my time in Japan, I was a derivatives trader and then ran a hotel investment fund. The anecdotal similarities Ken and I saw between Japan in the late 1990s and the global scenario unfolding before our eyes over the last two or three years prompted our investigation into deflation and negative interest rates. The question we posed ourselves was, “What is the chance that the deflationary Japan trap goes global?”
Writers’ Disclaimer
Before explaining our current thinking on the deflationary trap, I would like to make two points abundantly clear. The first is that neither Ken nor I are economists or have any formal training in economics. We start from a very practical perspective: to seek to inform our investment decisions. We consider ourselves “armchair economists,” such that academic economists’ theories do not engage us particularly. We prefer to see the world in high resolution where the majority’s individual choices will ultimately prevail regardless of the macro statistics.
Second, what we layout in the following is not what we believe will happen. Ken and I set up a hypothesis – that the world is sailing towards a long period of material deflation – and now seek to disprove our hypothesis. Unfortunately, on that front, so far, we have failed.
The Japan Deflation Indicators
What started Ken and I investigating this world of deflation? Three indicators set the alarm bells ringing for us. These are the conditions that we hypothesize are necessary to create the conditions that result in the “Japan Trap.”
- Massive amounts of debt in the private economy and on and off government balance sheets worldwide, including debt securities and obligations such as healthcare and pensions.
- Large numbers of poorly performing debtors. These are sometimes referred to as “zombie companies.” Generally defined as companies that are unable to earn a return sufficient to service their outstanding debt. This is the corporate equivalent of paying off your credit cards with more credit card debt.
- A stagnating population, in particular a stagnating working-age population that is subsequently going to go into decline.
Where To Start?
These are complex areas to explore, even for someone who has been involved in the markets for many years. It has involved a great deal of reading and thought to craft our hypothesis. Along the way, two books have impacted our thinking significantly. The first is called Capital Returns, edited by Edward Chancellor. The second is The Great Wave by David Hackett Fischer.
It Is All About Returns
Let us look first at Capital Returns. This is a compilation of investment letters from Marathon Asset Management to their investors from 2002 to 2015. It is an excellent read and worthwhile for anyone interested in the financial markets. Marathon follows an investment process based on investment cycle theory. They look at industries and see investment cycles, the location of any industry in a cycle can be identified by the quantum of investment.
It can be summarised as follows. When investment in a particular industrial segment is high, the additional investment tends to compete away equity returns. Eventually, this leads to a process of capital destruction when supply exceeds demand. Once the capital destruction process has occurred and the industry is “right-sized,” then equity returns increase, and the cycle of attracting investment starts again. Crucially, the point to observe is that once debt levels rise above a critical point, equity returns tend towards zero and ultimately turn negative as capital is destroyed. This is a necessary process that has to occur before equity investors can enjoy returns once again.
Marathon observes that the investment cycle works at the company level, across an industry, and also for an entire country. Look, for example, at Japan. The broad TOPIX large-cap index garnered lots of headlines recently when it reached a 30-year high. But not every article bothered to mention it is still 30% below its all-time high of December 1989, the peak of Japan’s massive debt-fueled bubble. Is the world about to explore whether this investment cycle proposition holds true across multiple economies simultaneously?
History Provides Situational Awareness
The second book is one of history. Something that struck Ken in particular as we went through our discussions was how much of the accepted body of economic theory had been written in the 20th century. In the grand scheme of things, this is a particularly short period when considering our economic future. The Great Wave provides a much larger context to consider as it starts its analysis from the twelfth century. The author does a fantastic job of tracking prices and socio-economic cycles from the twelfth century to the late twentieth century.
The critical understanding we both took from this book (with sincerest apologies to Drs. Friedman and Schwartz) is that it seems highly unlikely that inflation is a monetary phenomenon. It seems more likely to have been driven by population. The analysis that leads us to this conclusion is laid out in historical terms in the book. Still, interestingly, periods of deflation appear to have been as common as periods of inflation before the 1930s. I find it intuitively correct that inflation (or even deflation) results from the summation of many billions of individual human decisions rather than something that can be imposed on society by central banks at a whim.
Back to Today
If we bring the discussion back to the current situation today, this does appear to be consistent with the Japanese experience. As we broaden our perspective and look at several European countries, like Italy, Spain, and Portugal, they seem to be following closely in Japan’s footsteps. They have high levels of government borrowing, population stagnation or decline, and significant bad debts in the banking system.
When Ken and I took a step back and reviewed the last 800 years of inflation and deflation cycles as laid out in The Great Wave, it provided a new perspective on the academic orthodoxy that seems to rule in finance, economics, and thus government these days. All the modern ideas of interest rates, inflation, and deflation have been formulated during an era of unusual population growth. It would appear that if we selected a single day at random prior to 1890, it is just as likely that inflation was being experienced as deflation on that day. Furthermore, during the three Great Waves that preceded the current wave we are in, the average annual rate of price inflation was less than 2%. This is a far cry from the average of the current Great Wave of over 4%. It appears that inflation is not the default but this “modern” wave is the highest rate of sustained inflationary increase, by far, in known human history.
This boom in inflation over the last 90 or so years has also coincided with the most significant increase in the human population on the earth. It also poses the question of whether the most recent academic literature that focuses on these issues suffers from recency bias? Even if that “recency” happens to be the last 130 years of economic history.
Banks In A Deflationary Environment
What if we happen to be right about this? What if we have entered a protracted global deflationary (or, at least, non-inflationary) environment? What are the practical implications? How might the world look?
Going back to the comments of our fund manager, he posits that “…the idea that someone pays you to borrow money is ridiculous.” Well, is it?
For every transaction, there need to be two parties, the borrower and the lender, and there must be an incentive for both sides to enter into the transaction. First, let us consider a lending transaction by a bank in a severely deflationary environment. (Warning: Things will get strange from here. Your brain might hurt.)
Deflation – The Banks Still Win.
For ease of illustration, I have chosen large numbers. These are in no way meant to be a prediction of the future but are selected so that hopefully, the economic incentives are more apparent. Let us consider a country where deflation is -5%, and the deposit rate is at -4%. The bank will continue to make a sound interest rate spread if they lend the money at -2% per year. This means the bank will pay their borrower 2% of the loan amount per year to take on the loan, and the bank will make a 2% interest rate spread as they can borrow money at -4% (i.e. remove 4% of your money from your bank account every year on average). Furthermore, let us assume the bank will receive back its principal at the end of 5 years in a non-default scenario.
The bank should be happy with this transaction. Deflation has been increasing the purchasing power of each unit of money at the rate of 5% per year. The magic of compounding means that at the end of the five-year loan, the unit of money the bank has lent now has a purchasing power that is 27.6% more than the original unit lent.
Let’s look at the same transaction on a deflation-adjusted basis. The borrower will have received 1.104 of value for each unit borrowed (initial principal plus the coupons they received) and paid back 1.276 units.
This is the opposite of how we typically think of debt. In an inflationary world, the purchasing power of money reduces over time, and thus the burden of debt falls over time. In the deflationary world, the real value of debt increases over time. The clear conclusion is that this is a logical transaction for any bank to consider in a deflationary world.
Deflation For The Borrower
The other side of this equation is the borrower’s perspective. This is where things become interesting. This is also at the crux of our disagreement with our fund manager. He posits as follows:
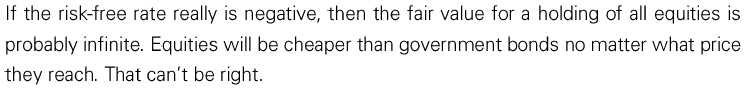
We do agree that what our money manager laid out is not correct. Their suggestion is that if anyone can borrow money at a negative interest rate, then the value of assets is infinite. But is this correct in a deflationary environment?
This deserves more investigation. I will start by assuming that if interest rates are negative to any significant extent, deflation is in control. For the consumer, at street-level, the easiest way to think about this is any item or asset’s nominal price will be less tomorrow than it is today. This process has been at work in Japan for decades and one that I found normal after very few years of living there. It was particularly pronounced with the price of beer, something I celebrated.
Borrowing Money In Deflationary Environment
Any borrower in a deflationary environment would find himself in a difficult situation. Let us assume that, in this case, the borrower purchases a piece of real estate. With deflation in control, the nominal value of the property decreases with every day that passes. Yet, the value of the loan remains constant (and is increasing in real terms). Where do these losses materialize? We suspect through the destruction of equity.
To illustrate this further, consider Landlord A, who takes out a loan and builds a tower block with deflation running at -5%. Landlord B comes along five years later to build an identical and competing tower block. He can build it for 27.6% less than Landlord A. This means that Landlord B can have cheaper rents (potentially 27.6% cheaper) and provide a newer product to the market yet still make the same or better return on his invested capital than Landlord A. To add insult to injury, the loan Landlord A took out to build his tower block is larger in real terms, and the nominal value of his property has dropped in line with deflation. Here is the destruction of equity.
Being Paid To Borrow Money – Not As Good As It Sounds
Our fund manager said the idea “…that someone pays you to borrow money is still ridiculous.” Based on our thinking, it is perfectly logical. The only problem we see is that banks cannot pay enough for anyone to want to borrow money in a deflationary environment! In any logical lending situation where the bank is making money, the borrower will be in a losing position because their equity will be reduced merely with the passage of time.
Returning, once again, to Japan is quite illustrative. Over the last ten years, the Bank of Japan’s balance sheet has increased over seven times and now exceeds 100% of GDP. The country’s largest hedge fund…sorry, the central bank owns 45% of all outstanding Japanese Government Bonds and $344 billion of equities.
If our fund manager is correct negative rates lead to stratospheric equity valuations. So what happened in Japan? If unhinged money printing leads to runaway price increases, why is my donut in Japan 20% less than it was 20 years ago? Deflation appears to be as ingrained as ever in the land of the rising sun.
Japan Is Different, or Is It?
This is a conundrum Ken and I continue to debate, and the best explanation we have come up with is that when interest rates fall close to zero, it portends deflation. The low rates do not ignite the animal spirits of borrowers – borrowers are logical. What does happen is that demand for loans collapses, people choose not to borrow, and the velocity of money falls. All the money accumulates in the financial system. Very little is deployed into the economy at the grassroots level resulting in a massive balance sheet at the central bank level. This describes Japan.
So do we think this is a potential outcome for the major economies of the world? Specifically, and at such levels, maybe not. But generally, yes. As with all things of the future, I am sure what we have laid out here will not transpire. What is of crucial interest to Ken and I is to understand how we get to the next bout of inflation. Are we about to return to a world of inflation after a bit of a deflationary wobble? Or will we be entering a period of deflation and equity destruction to return to inflation ultimately?
The majority appears to believe we are heading to rampant inflation. We believe we have laid out a reasonable outline of the alternative from a very different perspective to those in the financial orthodoxy. We invite those interested in challenging our hypothesis to join the discussion here. Ken and I have failed to destroy our own hypothesis, which could be for many reasons. We are keen to find our errors and are fully aware of our scholarly limitations. So, for those who have spent more time on this than we have and have insight and understanding to help us course-correct, please fire away. We would be most appreciative.
Technology Dictating Your Life?
“In this “information overload” age I realised technology was dictating my time. I wanted to take back control of time, my time! …[SNGLRTY] propelled me on my journey to take back time. It’s unique, personal and is more than just a watch.”
Configure Your SNLGRTY >
I love this article: too few of these pieces are written by people that have actually lived with deflation. The key comment in there is that there will be no price at which people will be prepared to borrow money in a deflationary environment (because of course buying a depreciating asset on leverage makes little financial sense: instead of multiplying your gains, you multipy your losses) which is not something I’d thought through properly before.
Thank you Rick. Exactly, the banks will not be able to pay enough for people to take on the loans. It does beg the question, what would happen next as the pressure builds up on the ever-decreasing equity buffers?
A fascinating (if brain-contorting) article! Lots to consider – and I should point out that I am not an economist, I am a businessman with 20+ years experience of making things & trading things & project managing things in various international environments, having lived & worked abroad for about a third of my career. I’ve worked in multiple industries including aerospace, defence & construction in everything from SMEs to big multi-national blue-chips. And I can safely say (without fear of contradiction!) that I’ve never experienced a more bonkers time or working environment!
What follows is a selection of random thoughts and snippets which may stimulate different ways of viewing the current situation. I have no particular answers, other than to urge people in times like these to keep an open mind, be prepared to change their mind – substantially, frequently, and in directions they never thought they would!!
First a general observation – you are still viewing the markets in terms of equity, value and where you can skim something off other people’s hard work. That is a valid enough point of view (and one on which the entire financial industry depends!), but it is not the only one. The individual people & companies (the acting agents) that aggregate to make up those markets do not all or always think the same way. And that means those actors will not necessarily act in ways that the “financial players” would expect based on models and classical economics. To take an example – in the deflationary world, why would anybody buy a house? Why not just rent, and get the double benefit of dropping rents and no destruction of equity (as well as the millstone of negative equity risks)? Well, people recognise that deflation cannot last for ever, and people like owning things. And what about putting a shiny new kitchen in that house whose value is dropping like a stone? Well, sure, if you only think in terms of the “asset value” of the bricks & mortar, it makes no sense. But if your kitchen is old & falling to pieces, you may either need to replace stuff, or just want to spend to live in a nicer place. Hell, why not? You might wait a bit longer, you may choose different things to buy, but you won’t just watch the walls crumble around it – at least if you can afford to spend what you need/choose to spend.
Borrowing – a great many borrowers are financially pretty clueless. In a world of cheap money, over-supply of shiny goods made in sweat shops in the far east and people who are working harder for less gain in crumbling societies, borrowing has become too easy, too aggressively promoted/advertised and has become a “drug” to numb the senses from the reality of the imploding societies around them. You might be in a low or average wage job, slogging away and not really able to afford the shiny things – but, hell, if the bank is going to let me have it anyway on the never-never, why not? and, of course, if a huge proportion of these shiny things are being made by (effectively) slave labour at costs well below “true” values, then the disconnect from reality is all the greater so people can hide from the true unaffordability of what they are spending.
And “disconnect” is a big theme for me. Particularly the disconnect in the “signals” which a properly functioning monetary system sends to all actors within the system. A leap fron 5% interest to 10% sends an important signal. A drop from 0.5% to 0.25% is lost in the noise! And think also of the strange position now where even well-paid, moderate to high-earners who, previously, would have prudently minimised borrowing or sought to avoid it altogether – they, proportionately, have taken on bigger debts, because money was cheap, and they knew they could easily pay it back. Their debt burden (and potential asset collapse) now is far higher than the lowest earners who needed to borrow to survive.
And this is where I think the world, courtesy of Covid, is heading for some major and very painful shocks. The lower paid (carers, nurses, shop assistants, lorry drivers, plunbers, electricians etc) are still “essential” within the economy. The £6 skinny-latte swilling advertising middle managers and diversity consultants are about to discover they are not.
To add insult to injury, it will also be a big swathe of the accountants, lawyers and other “professionals” who are about to discover just how rapidly technology has “dumbed down” large swathes of their skillset into easily repeatable, call-centre, tick-boxing activities which no longer require well-spoken, privately educated, intelligent folk to transact. That will be interesting to watch!
You mention the problem of “zombie companies”. I agree – I watch dozens of them in my industry every day, lumbering on from one poor decision to another, staffed by mediocre people who they should really remove. But the cheap money, the need for banks to lend etc means that they still keep going – again the “signals” of poor performance masked. Which leads to continued over-supply and prevents the “good” companies from forging ahead and setting prices at profitable levels which would get us back into a “positive” level of inflation.
Yet none of that is sustainable. Money cannot continue to be printed indefinitely without consequences. We fudged the last recession (and a half) and did not “take the pain” that was due. We released the banks from the necessity that is “moral hazard”. And now, armed with the knowledge that they’ll be bailed out again, no matter how badly they screw up, they’re at it all over again.
But something is different this time. There is an unease in the system, among normal folk. They sense that something isn’t right They know that there are disconnects – that people making bad decisions are not suffering consequences, but that their hard work isn’t bringing them their just rewards.
So a few things will happen. Are already happening, if you look carefully. First of all, discontent is growing and now starting to spill out onto the streets. It is being hugely contained, under-reported (there is no such thing as independent news now, only carefully managed propaganda & narrative) and Covid has provided an excuse to “kettle” it and remove rights for people to protest, organise, congregate & push back. But that confrontation cannot be postponed indefinitely. All that remains to be seen is who wins the inevitable battle.
Another group of folk, fed up with not making headway, are just sitting back and doing the bare minimum to not get fired. They’re not engaged (but not actively fighting against the system) – but they sure as hell are slowly killing companies & destroying value. Of course, the cheap money means that is being hidden – and so the zombie companies stagger on. For now.
A final notable group are those who see what is happening, dislike it, and understand sufficiently to “disengage” from the dysfunctional elements and are building little “islands of sanity” amidst the sea of craziness around. They’re exiting the rat race – following passions, building nice little solid companies WITHOUT debt, largely divorced from the wider money industry and with (they hope!) sufficient equity & liquidity to ride out the coming storm and then, maybe then, if sanity returns, ramping up the contributions they make to larger businesses and wider society. For now, though, they’re content to “live apart”, using their rainy day savings if necessary, while the turmoil engulfs those players not fortunate enough to live outside that system.
Because while I cannot predict whether the next moves will be inflationary or deflationary, I can comfortably predict that the world is about to enter a period of huge disruptions, change (economic, social, political & technological) that is unprecedented for most folk alive.
I am reminded of the concept of the “unpredictable motion of double/triple pendulums”. Seek out youtube videos to see what I mean. Even in a relatively simple system. the “motion” can become very unpredictable – can go one way then the other at high speed and with seemingly no rhyme nor reason. A lucky few sit at the “centre” of that pendulum system. The next most fortunate sit on the inner bar. God help the folk who are right at the end of the outermost one! And it may not be the people we think are there…
So what, then, to do in a world heading into chaotic times? Well, that’s up to each of us to decide. For my part, it is being part of the group which steps out of the craziness (for now, at least), to live life at a slower pace. To indulge a few of my passions, spend a little more time with people I like to be around, experiencing the things I would like to the best of my abilities and despite all the inevitable restrictions the governments impose as they franticly pull at levers which connect nowhere. And to help as many “like-minded” folk to do the same. And pick up some of the pieces from the wreckage the storm will cause.
Who knows – I might just have to enjoy adding to my watch collection (just a little!) while the spectacle unfolds…
You never know – we might get lucky and the banks get the come-uppance that they avoided at the start of the century! Though I rather doubt it…
Thank you Arctic Fox for a wonderful summary of your thoughts. I agree with everything you have said, the financial shifts that I wrote about are just a slither of changes that are coming our way, more likely than not. There is just too much for me to respond to in the comments but I may pick up on some of those themes in a later post. Thank you again.
Hi Steve – Love your watches, and your impromptu observations on the world at large.
Your blog post reminded me of a thorn in my side that has been around for the past 20 years, namely why Japan’s persistent deflation has been so widely misinterpreted, and why the Bank of Japan’s efforts to overcome it have been so flawed.
Not long ago I wrote a comment to help (in my humble opinion) understand this conundrum. With your permission I will share it with your readers.
First, I am glad to see you and Ken doing the Big Think about this odd conundrum of how and why financial markets manage to blithely sail across these stormy and unpredictable seas, with all these “distortions” and apparent “contradictions.” Such as – duh – negative interest rates, massive bond and equity issuance, and the scorn directed at market pessimists and bears. (I am a realist and believe markets will hit a yet-unseen landmine of some sort and take a deep dive, but am also an optimist to have faith we will once again recover. Excess is in the mind of the observer, and when the Mississippi overruns its bank, in the mind of the home-owner in the flood-zone.)
Second, I am equally happy to see that both you and Ken remain interested in Japan. Most big money players are back to where they were a decade ago, dismissing Japan, in fact if you go back TWO DECADES, there was Alex Kinmont pompostulating (my word), that “Japan is of no interest any longer, except as a textbook case of deflation.”
Within a few months, Japanese equities roared back and did not falter until the Horiemon arrest and the collapse of his clever hoax, which as with so many hustlers and scamsters was basically to make people believe that money grows on trees. He made a fortune splitting down shares of Live Door about 15-16 times in 2-3 years, for example, and was paid ¥150,000 per attendant at his popular “how to become rich like me” seminars.
Going back to Kinmont, he had made the classic cognitive error of believing he knew better, but Alex only “knew” anything from what his well-connected friends told him. In other words, he had filtered his thinking so heavily, he only saw what fit his predisposition – which was to be negative on Japan, regardless. Jim Grant and all his friends were like that, as you know.
I remember at the time thinking, oops, Alex is missing something right there in the data, if only he knew where to look and what it meant: The Baltic Dry Index had started going ballistic that winter, so much so Japanese shipping execs were saying stuff like “to be honest, it is embarrassing how much money we are making right now….”
Third, I have written extensively on the cognitive mistakes that Kuroda and his colleagues (as well as the LDP “brain trust” who pushed Abenomics to an initially very reluctant then “former prime minister” Shinzo Abe back in 2012) had made and continue to make. 3-4 years ago, I met routinely with senior BOJ execs who stopped by for a monthly not-for-attribution briefing at the FCCJ.
Here is the mistake and it has severe consequences (at least in my view): First of all, Kuroda-san came out of the Todai law faculty like all his peers at MOF, and served as head of the Asia Development Bank, a largely ceremonial role to project Japanese Soft Power in Asia.
OK, I promised to be brief so hang on just for a minute or two.
For most of the 20th century, the Monster In the Closet was called inflation. Deflation was rare, like some never seen only rumored orchid from Sumatra.
So, Milton Friedman made the famous Nobel-winning observation that “inflation is always a monetary phenomenon, where the quantity of money in circulation exceeds the quantity of goods” (my paraphrase).
Fast-forward to the opening of the 21st century, and deflation has been chewing on Japan’s economy for nearly a decade already, since the collapse of the Bubble Economy in 1992, that famous lost decade. The analysis: Go back to Friedman and flip his inflation notion on its head – by George, I think we’ve got it – and jubilate in finding the (wrong) answer namely that the money in circulation is insufficient in relation to the quantity of goods.
The remedy: Print money.
The BOJ has been doing it constantly for 20 years, heedless of Einstein’s observation that the essence of insanity is to do the same thing over and over and expect a different result.
It does not appear to have occurred to Kuroda & Co. that Friedman may have hidden the real answer right there, in open view, namely that the quantify of goods exceeds the quantity of money, so the remedy is to reduce the output of goods (and services).
So Steve, when you are back in Tokyo – walk into any Japanese shopping center, or any store for that matter: A MASSIVE OVER-SUPPLY of everything, like UNIQLO, ever increasing floor-space with an ever-increasing supply of men’s and women’s undies. Walk into any Yodobashi or BIC Camera and go take a look at the vast floorspace dedicated to selling large flat-screen TVs, 55 inch, 65 inch, 75 inch. But who needs them? Who wants them? Until the recent chip shortage, try the car dealer, the used car dealer. Over in Kofu there are huge parking lots full of little Honda kei-cars. They have ostensibly been sold and registered, by one part of Honda to another. Gotta keep the factory running, the excess inventory will take care of itself.
How? The same way Uniqlo and everyone else does. Cutting prices. Honda will sell those “used cars” with only 150km on the odometer (the distance to the factory in Saitama) at a discount.
No amount of money poured into the banking system will cure that. Banks are AWASH in cash, hence the negative rates.
Negative interest rates are an obvious result of excess cash, not in circulation per se, but in the banks, sitting there idle, with no demand for credit, and so the credit multiplier itself may have gone to less than 1x, whereas in a bubbly economy it goes to 4x, 5x. Friedman himself was wrong, by the way. It is not “always excess money” it is “always excess credit” as we all know intuitively. With a credit multiplier of 4x, the credit far exceeds the amount of “money” and the cash itself M2 and all that severely under-counts the actual and problematic credit.
I will stop here, but it is also true that BOJ money-printing likely made deflation worse. How? By taking spendable cash (in the form of interest earned on savings) out of the wallets and hands of consumers, ie. punishing savers for having cash in the bank. Normal interest rates of say 1.5% on savings (or more) would generate trillions of yen in disposable income for households.
BUT INSTEAD, BOJ mandated zero interest rates have robbed households of that spendable income for TWENTY MIND-BOGGLING YEARS now. Trillions of yen they have “purloined” every year.
This is what I call “policy-induced destruction of demand” which you can rephrase as “policy-induced deflation.”
I rest my case. For now anyway. Happy to elaborate – though you may not be!
Steve,
I thank you!
Only a generation ago, one assumed that the human race, if it could do nothing else, could make babies and cheapen the value of paper money. Now look. We can’t do even that.
I really enjoyed your paper, especially the wisdom distilled in the line, “the majority’s individual choices will ultimately prevail regardless of the macro statistics.”
Where I think we may differ is in our respective readings of the meaning of that mountain of negative-nominal-yielding debt. For me, it’s not the market talking but the central banks buying. My hypothesis (like you, I’m retailing no forecast) is that the lowest interest rates in 4,000 years is the product not of demographics but of the overlay of muscle memory (the bond bull market is 40 years old) and our historically unique monetary arrangements. In other words, I can’t—though you can—explain why sentient investors are willing to buy debt obligations denominated in the very currencies that central banks are pledging (slowly) to destroy.
Tell you what: You buy bonds, I’ll buy gold and, when we next meet, I’ll buy beer.
In one paragraph, you have put up the most robust argument against our hypothesis! Brilliant. I need to let that ruminate in my head for a little while, but I feel another bit of writing coming on.
Although I leave you to ponder this one. If the central banks are buying and depressing the yield curve in an attempt to get inflation into the system, and this is exactly the path the Bank of Japan has trodden, why is there no inflation in Japan? Or what is different I the US to Japan and increasingly Europe?
As for bonds versus gold, I believe that gold will win in both scenarios – but there has to be a significant move. Gold will be the loser if there is a path to just “muddle through” the current predicament.
We can go Dutch on those beers, I think.
Steve
Thanks for these deep, mind-bending insights!
I wonder to what extent the following two trends would work against the deflation thesis you laid out:
1. State-sponsored demand generation might increase market interest rates. This argument expands on an idea that Thomas Piketty laid out in his recent book Capital & Ideology. The mechanism would work as follows: if voters elect governments that undertake massive redistribution to address social inequities and finance the transition towards a green economy, then a) high earners will accumulate less capital due to a combination of higher income taxes, higher wealth taxes, higher inheritance taxes, b) some of those funds will be directed towards government-led investment (i.e., potentially raising demand for capital, though in the process likely crowding out private sector investment), and c) some of those funds will be directed towards raising consumption (e.g., universal basic income or similar subsidies for low earners). The net result could be less supply of capital, more demand for capital, and higher returns for some kind of investment. However, this rising rates scenario would also make high government debt less sustainable.
2. Central banks will have functional central bank digital currencies as part of their modern monetary theory efforts. The next time markets encounter a “whatever it takes” moment, money could be directly deposited into consumers’ bank accounts. Particularly if central banks become more inclined to bend to the will of populist politicians. Unlike today and (I’m guessing) the Japan-since-1989 example, this could mean that more of the expansion in the monetary base shows up directly in consumer’s pockets. Other things being equal, that should create inflation.
Both #1 and #2 seem to reflect the direction of travel in several advanced economies. I am not arguing this would negate the power of demographics in the long run though. For instance, if the older cohort owns assets at inflated prices, then one way this could unwind is simply that the younger cohort lacks the capital to become the next generation of owners (particularly where inheritance taxes are high like in much of Western Europe.)